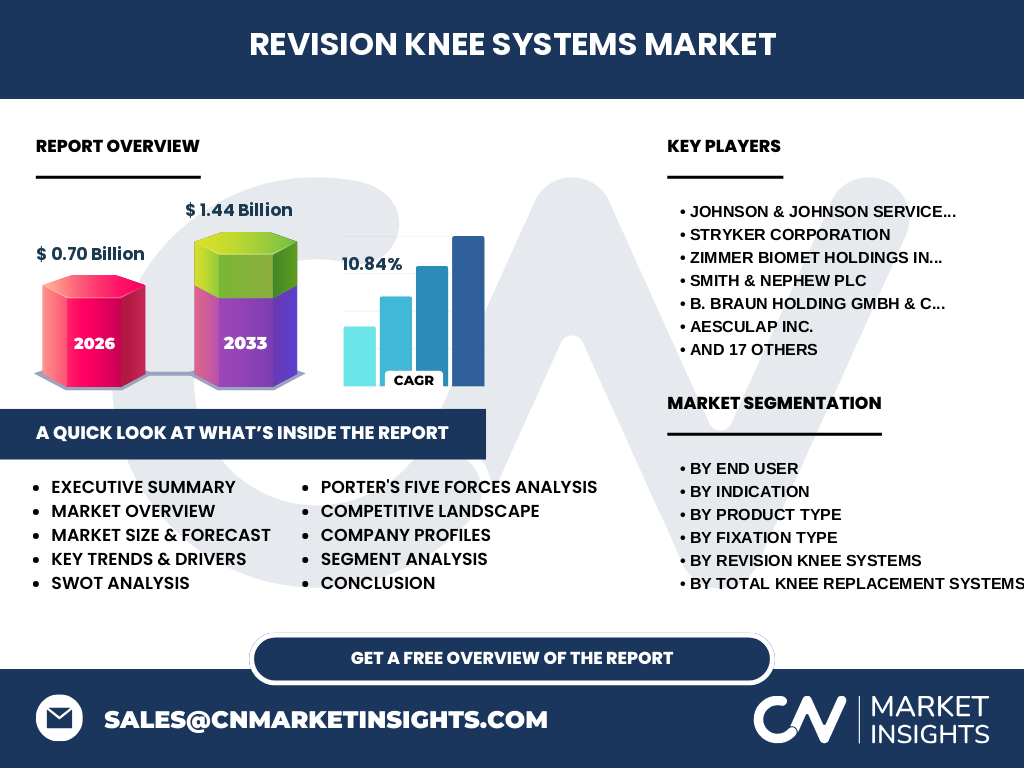
Market overview and industry significance of the Revision Knee Systems Market
Our analysis indicates the Revision Knee Systems Market represents a highly specialized sector focused on complex joint reconstruction procedures. With a baseline valuation of $0.70 Billion in 2026, this industry addresses failed primary arthroplasties due to complications like aseptic loosening and infection. Advanced metallurgy and precision instrumentation are critical for restoring patient mobility and joint stability.
Structural Growth Drivers and Market Restraints
The market is propelled by rising primary knee arthroplasty volumes and an aging global demographic prone to implant wear. However, growth is restrained by stringent regulatory clearance protocols from bodies like the US FDA and high procedural costs. Surgical complexity further limits widespread adoption in resource-constrained ambulatory surgical centers.
Emerging trends and growth patterns in Revision Knee Systems
Industry trends highlight a decisive shift toward patient-specific instrumentation and 3D-printed porous titanium components. These innovations enhance osseointegration in challenging bone defect scenarios. Custom augments and metaphyseal sleeves are rapidly gaining clinical preference among orthopedic surgeons seeking reliable long-term fixation alternatives.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic caused a sharp contraction in elective orthopedic surgeries, significantly delaying revision procedures worldwide. Supply chain bottlenecks for medical-grade cobalt-chrome and titanium raw materials worsened logistical hurdles. Surgical backlogs have since fueled a robust recovery trajectory, with procedural volumes rebounding above pre-pandemic baselines.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is consolidated among multinational medtech leaders like Zimmer Biomet Holdings Inc. and Stryker Corporation. These giants leverage extensive global distribution networks and proprietary knee portfolios. Meanwhile, agile players such as Medacta International SA and Meril Life Sciences capture share through specialized, high-flexion revision implants.
Executive Summary of the Revision Knee Systems Market
Our proprietary research confirms the Revision Knee Systems Market is poised for accelerated expansion, reaching $1.44 Billion by 2033 at a robust CAGR of 10.84%. This growth is driven by technological advancements in revision stems and a surge in complex knee revision surgeries globally.
Market Forecast and Long-Term Trajectory from 2027 to 2033
Based on our econometric modeling, the market will scale from its 2026 baseline of $0.70 Billion to achieve $1.44 Billion by 2033. This sustained 10.84% CAGR reflects increasing revision rates driven by younger, more active patient cohorts experiencing premature primary implant failure.
Segmentation Analysis by Product Type, Fixation, Indication, and End User
The market segments by product into Revision Knee Systems and Total Knee Replacement Systems, categorized further by femoral components, revision stems, and metaphyseal cones. Fixation divides into cemented and cementless variants. Indications span aseptic loosening, infection, instability, and periprosthetic fractures across hospitals, orthopedic clinics, and ambulatory surgical centers.
Geographic Distribution and Regional Market Analysis
North America dominates global consumption due to advanced healthcare infrastructure and high revision procedure rates. Meanwhile, the Asia-Pacific region exhibits the fastest growth, propelled by expanding healthcare expenditure, rising medical tourism through ports in India and Southeast Asia, and improving access to specialized orthopedic care.
In-depth Regional Review of Regulatory and Logistical Realities
Strict oversight by the European Medicines Agency and US FDA shapes regional product lifecycles. Logistical precision is vital for distributing bulky instrumentation trays to operating rooms. Reimbursement policies heavily dictate hospital procurement choices across Western European and North American markets.
Company Profiles and Strategic Positioning of Leading Participants
Industry leaders like Johnson & Johnson Services Inc. and Smith & Nephew plc emphasize digital ecosystem integration and robotic-assisted revision surgery. Regional specialists such as Waldemar Link GmbH & Co. KG and United Orthopedic Corporation focus on modular implant designs to address severe bone loss.
Porter's Five Forces Analysis of Competitive Pressures
Rivalry is intense among established orthopedic conglomerates, while the threat of new entrants remains low due to high R&D costs and strict regulatory barriers. Bargaining power of buyers is moderate to high, as hospitals demand cost-effective, modular implant systems from suppliers like Enovis Corporation and B. Braun Holding GmbH & Co. KG.
SWOT Analysis of the Revision Knee Systems Market
Key strengths include advanced biomaterials and robust modular implant designs. Weaknesses involve high surgical costs and steep learning curves for complex instrumentation. Opportunities lie in emerging market expansion, while threats include pricing pressures and stringent reimbursement cuts by regulatory authorities.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing medical-grade titanium and cobalt-chrome alloys. Manufacturers process these materials into revision stems, wedges, and polyethylene inserts. Distribution relies on specialized medical logistics servicing major hospital networks and ambulatory surgical centers worldwide.
Investment Insights and High-Potential Strategic Areas
Investors should target companies specializing in cementless revision knee systems and 3D-printed metaphyseal cones. Firms partnering with digital navigation and robotics developers offer superior growth potential, aligning with clinical demands for improved alignment and reduced revision failure rates.
Conclusion and Key Takeaways for Industry Stakeholders
The Revision Knee Systems Market offers compelling investment opportunities, underpinned by a projected 10.84% CAGR through 2033. Success requires continuous innovation in modular components, strategic geographic expansion, and close alignment with hospital value-based procurement initiatives.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived by triangulating data from primary stakeholder interviews with orthopedic surgeons, trade registry statistics, and secondary macroeconomic indicators. This rigorous methodology ensures accurate market sizing, accounting for procedural volume variations and regional ASP discrepancies.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for revision knee systems from 2026 through 2033. Parameters encompass detailed evaluations of product types, fixation methods, indications, and end-user segments, while excluding primary joint replacement procedures and non-knee orthopedic reconstruction devices.
Recent Developments and Strategic Industry Moves
Recent strategic moves feature product launches incorporating advanced porous coatings and acquisitions aimed at strengthening global distribution footprints. Innovators like Corin Group Limited and Maxx Orthopedics Inc. continue to invest in clinical registries to validate the long-term survivorship of their revision portfolios.